Four tiers of capital: how a private investment company thinks about allocation
People sometimes ask how a private investment company in Bloomfield Hills, Michigan decides where its money goes. The answer is less about picking winners than about keeping four kinds of capital in their proper places. Creek Equity's Investment Policy Statement divides everything we hold into four tiers, and nearly every decision we make starts by asking which tier it belongs to.
Core capital
This is the foundation. Its job is preservation across generations, not performance in any given year. It lives in investment-grade fixed income, broad and blue-chip public equity, and income-producing real estate. We do not take risks with core capital to chase a return, however attractive the opportunity looks. Its clock is measured in decades.
Growth capital
This is where Creek Equity does what it is known for. Growth capital funds the companies we found, the founders we back, and the businesses we acquire, alongside private equity and venture fund commitments. It accepts higher risk for higher return and expects to be illiquid for five to fifteen years. Most of our direct investments live here, and they are the majority of the tier.
Aspirational capital
A defined share of what we hold is directed to purposes beyond financial return: impact and mission-aligned investments and philanthropic vehicles. We measure these on the outcomes we agreed to at the time of commitment, and we hold them with patience. This tier is how our values show up in our balance sheet rather than only in our conversation.
Liquidity reserve
Cash, Treasury bills, money market, and short-duration credit. The reserve exists so that no obligation, no capital call, and no opportunity ever forces us to sell a long-term asset at the wrong moment. It is sized to a minimum of twelve months of known obligations, and part of it is deliberately kept available for an investment nobody planned for. The best deals rarely arrive on schedule.
Why the tiers matter
The discipline is in keeping them separate. The temptation, when a growth opportunity is compelling, is to reach into core capital or draw down the reserve. The policy says no, and the policy was written on a calm day for exactly that reason. Rebalancing follows written triggers, not mood. New capital goes to the underweight tier first. Realizations come back to the allocation process rather than being reinvested automatically where they came from.
None of this guarantees a result. What it does is make sure that one bad year in one tier cannot undo ten good ones in another, and that when the right Michigan business comes along, we have both the capital and the patience to buy it.
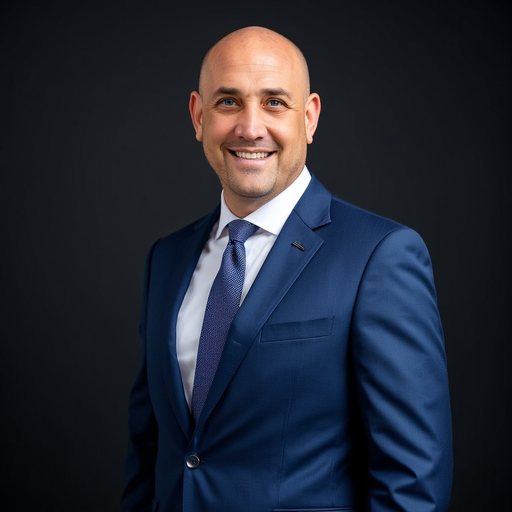
Scott Zack is the owner of Creek Equity, a private investment company in Bloomfield Hills, Michigan that founds, funds, and acquires businesses. He played forward for the Ohio State men's basketball team and has spent more than two decades building companies in Michigan. Read more about Scott.